Mexico aims for 50% digital payments within a year, on SPEI, CoDi and DiMo
Mexico is trying to do in a year what took other countries a decade: the Digital Economy Law initiative targets digital payments reaching 50% of the total in the strategy’s first year, cutting cash use toward 2027 — on rails the country already built: SPEI, CoDi and DiMo, from Banco de México.
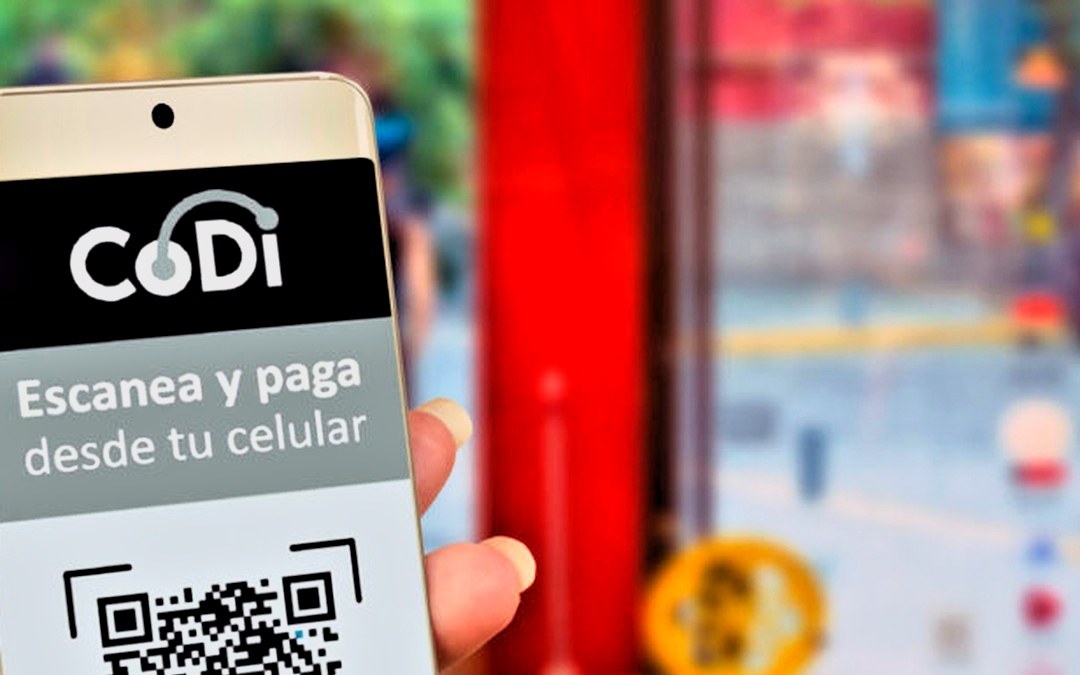
Photo: Banco de México (official CoDi system artwork).
The rails exist. The usage doesn’t — yet
Mexico does not start from zero: SPEI moves money in real time, and Banco de México’s CoDi and DiMo platforms are live. The gap is adoption. With operating data to July 2026, CoDi accumulated 23.2 million validated accounts against a target of 37 million, with 21.5 million accumulated transactions, and DiMo had 11 million linked phone numbers. The infrastructure is built; the habit is not. The initiative’s stated challenge is exactly that distance — between what the system can do and what people actually do at the counter.
The reference point everyone cites is Brazil’s Pix, which in 2025 processed almost 80 billion transactions, according to Brazil’s central bank — in the second half of 2025 alone it concentrated 54.7% of payment transactions. Pix is the proof that a public rail can become a country’s default gesture in a few years. Mexico’s bet is that its rails, older than Pix in SPEI’s case, can be pushed to the same ubiquity by law, targets and the humble QR code: for the person paying in a shop, the change is scanning a code with a phone instead of handing over cash.
The decision this sets
For banks, fintechs and merchants, a 50%-in-a-year target converts payments from a product roadmap into a compliance-adjacent race: acceptance points, QR coverage and onboarding friction become strategic this quarter, not someday. Felipe Vallejo of Fintech México and José Antonio Peña Merino of the digital transformation agency (ATDT) are among the voices framing the push. For small merchants, the decision is simpler and harder: the toll road of card fees now has a free rival, and rivals with state backing tend to win slowly, then suddenly.
Three rails, three jobs: how SPEI, CoDi and DiMo fit together
The names travel together so often that they blur, but the three systems are three distinct layers of one machine, and the strategy makes most sense when they are separated. At the bottom sits SPEI, Banco de México’s interbank payment system: the settlement layer, where value moves between accounts at different institutions in real time, finally and irrevocably, around the clock. SPEI is the vault-to-vault railway — invisible to shoppers, indispensable to everything built above it. When people say Mexico “already has the rails,” this is the rail they mean: a public, real-time settlement infrastructure that banks and fintechs plug into rather than build.
CoDi is the layer the customer touches. Built on top of SPEI, it turns a payment into a gesture: the merchant presents a QR code or a payment request, the customer scans or approves it in their banking app, and the money settles over the rail underneath — no card terminal, no card network toll, no waiting for a batch at the end of the day. Its design bet is that the phone in the customer’s pocket and a printed code at the counter can do the work that expensive acceptance hardware does elsewhere. DiMo attacks the other half of the friction — addressing. Instead of exchanging long account numbers, DiMo lets a phone number stand in for the account: 11 million numbers are already linked, which means 11 million people can be paid by the identifier everyone already knows by heart. Alias addressing sounds like a convenience feature until you watch someone dictate an account number digit by digit across a market stall; then it reveals itself as what it is, an adoption technology.
Read the adoption figures again through that layered lens and the strategy’s logic sharpens. CoDi’s 23.2 million validated accounts against a 37-million target, and its 21.5 million accumulated transactions, describe a system whose installed base is real but whose reflexes are not yet formed: accounts exist that transact rarely, merchants equipped who are not asked, customers equipped who default to cash or card out of pure muscle memory. Payment habits are among the stickiest behaviors in an economy — they are formed at counters, under time pressure, in front of queues — which is why a law-and-targets strategy is not decoration on top of the technology but an attempt to intervene in the habit loop itself: more acceptance points making the digital option present, more present options making it normal, normality doing what no campaign can. Brazil’s Pix, with its almost 80 billion transactions in 2025, is the standing proof that the loop can flip at national scale; Mexico’s wager is that owning the rail early, as it does with SPEI, is an advantage that only needs the last mile of behavior.
For the managers reading the target — 50% of payments digital in the strategy’s first year — the decision calendar is unforgiving in a useful way. Banks and fintechs have to treat onboarding friction as lost market share: every extra step between a customer and a validated account is measured, eventually, in the gap between 23.2 million and 37 million. Merchants face the mirror-image choice: the QR at the counter costs almost nothing to offer and increasingly something to lack, in customers who arrive expecting it. And for the small merchant doing the arithmetic at the till, the comparison is the one this magazine exists to make plain — the familiar toll of card acceptance against a public rail designed to move the same money without it, with the state, the central bank and now a legislative target all pushing in one direction. Rails do not win arguments; they win repetitions. Mexico has a year to collect them.
What thrills
- Public rails, private energy: SPEI/CoDi/DiMo are built; the race is adoption.
- A free rival to card fees: for small merchants, the QR changes the math of every sale.
- Pix as the proof: Brazil showed a country can switch its default gesture in years, not decades.
What to watch
- Habit is the bottleneck: 23.2M accounts vs. a 37M target — the gap is people, not technology.
- One year is fast: the 50% target’s first-year clock will test every assumption.
- Cash is resilient: informal commerce has reasons for cash that QR codes alone don’t answer.
The data sheet
The initiative
| Field | Detail |
| Instrument | Digital Economy Law initiative |
| Target | Digital payments at 50% of the total in the strategy’s first year; less cash toward 2027 |
| Rails | SPEI, CoDi and DiMo (Banco de México) |
Adoption (operating data, Jul 2026)
| Field | Detail |
| CoDi accounts | 23.2M validated, vs. 37M target |
| CoDi transactions | 21.5M accumulated |
| DiMo | 11M linked phone numbers |
| Reference | Pix (Brazil): ~80B transactions in 2025; 54.7% of payment transactions in H2 2025 |
Sources
- Digital Economy Law initiative coverage (Nov 8, 2026): 50% target, SPEI/CoDi/DiMo, operating data to July 2026; statements by Felipe Vallejo (Fintech México) and José Antonio Peña Merino (ATDT).
- Banco Central do Brasil: Pix volumes (2025) and H2 2025 transaction share.
- Photo: Banco de México, official CoDi artwork.